info@greybeard.in
TDS On NRI Property Sales: The Complete Guide
How buyer-side withholding works for an NRI property sale, why a lower-deduction certificate matters, the post-2024 capital-gains position, and the limited 1 October 2026 compliance change — explained plainly.
By Ashutosh Bhogra · 13 min read · 1 September 2026 · Updated October 2026
- When an owner abroad sells, the buyer holds back tax before paying, under section 393(2), the old 195.
- The tax held back is not your final tax; a certificate on Form 128, applied for early, can lower it.
- From 1 October 2026, a resident individual or HUF buyer pays it on Form 141 with their PAN, without a TAN.
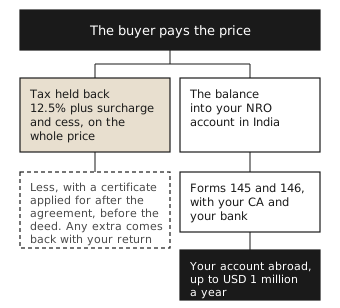
Where the money goes when an owner abroad sells.
For informational purposes only. Consult a qualified CA for advice specific to your transaction.
Selling Indian property from abroad normally involves tax being deducted before the seller receives the full price. That withholding is often described as TDS. It is not the same thing as the final tax calculation on your gain, and that difference is where planning matters.
What the buyer has to do before payment
For a non-resident seller, the buyer must address tax deduction when the sale amount is credited or paid. Older documents usually call this Section 195; the current Income-tax Act, 2025 places the non-resident payment rule in section 393(2). The tax process is different from the 1% resident-seller property procedure. Your CA should confirm the applicable rate, surcharge, treaty position, and filing route before the agreement is performed.
The practical point is straightforward: default withholding can be calculated against the sale payment, while your ultimate tax liability depends on the capital-gains computation and your own facts. Do not assume that the amount withheld is the amount finally payable as tax.
Long-term versus short-term: the calculation starts here
For immovable property, a holding period of more than 24 months is generally long-term; 24 months or less is short-term. For a long-term sale, the post-23 July 2024 base capital-gains rate is 12.5%. The position on indexation, surcharge, treaty relief, and your final liability needs to be worked out by your CA from the title file, acquisition documents, improvements, and transaction structure.
NRIs should not assume they have the resident taxpayer’s pre-23 July 2024 grandfathering choice. That option is restricted to a resident individual or HUF. For an NRI, the correct position must be calculated for the individual transaction rather than inferred from a resident seller’s example.
A simple distinction that prevents confusion
A property bought for ₹10 crore and sold for ₹20 crore has a nominal gain of ₹10 crore before allowable adjustments. A 12.5% base capital-gains calculation on that nominal gain begins at ₹1.25 crore, before any case-specific surcharge, cess, and tax adjustments. Default withholding can still be larger because it is handled against payment consideration. A lower-deduction certificate is the mechanism that can align deduction more closely with the estimated final liability.
Two certificates, at different points in the sale
A lower- or nil-deduction certificate is applied for by the seller before the sale, under section 395(1), on Form 128 (earlier Form 13). It tells the buyer to hold back less than the standard amount. Your CA should prepare the application from the actual property documents and tax computation; in practice, a signed Agreement to Sell is generally needed to make a property-specific application because it identifies the buyer, consideration, and payment structure.
The TDS certificate is given by the buyer to the seller after the tax has been deducted and paid, as proof. It is issued under section 395(4)(a), read with Rule 215, on Form 131 (earlier Form 16A). From 1 October 2026, a buyer who is a resident individual or HUF gives the certificate on Form 132 instead, within 15 days of the due date for Form 141.
Do not leave the lower- or nil-deduction certificate to registration week. It must be in place before the relevant payment is made and tax is deducted. Processing times vary by assessing officer and facts, so the seller and CA should plan the sequence well before the agreed completion date rather than rely on a standard number of days.
The limited 1 October 2026 buyer-side simplification
The Finance Act, 2026 gives effect from 1 October 2026 to a TAN exception for a resident individual or HUF buying immovable property from a non-resident. The provision is limited to the statutory buyer category and transaction. It does not change the seller’s underlying tax liability. The tax department set out the procedure on 22 September 2026 in Notification No. 121/2026 (G.S.R. 830(E)).
Tax held back up to 30 September 2026 stays under the old TAN-based process and is reported in the quarterly Form 144. The rules do not say how to link payments made on both sides of 1 October, so the buyer's Chartered Accountant should confirm this for such a deal.
From 1 October 2026, a resident individual or HUF buying from a non-resident pays and reports the tax on Form 141, Schedule E, using their PAN login on the income-tax e-filing site. Schedule B of the same form is only for a resident seller — do not use it for an NRI seller.
TDS evidence, return filing, and the credit record
The buyer’s tax deposit, reporting, and certificate obligations must be completed correctly for the seller to receive tax credit. A resident individual or HUF buyer must pay the tax with Form 141 (Schedule E) within 30 days from the end of the month in which it was held back. If there are two or more buyers, each files a separate Form 141 for their own share. Ask the buyer’s CA to share the relevant acknowledgement and certificate, then have your own CA reconcile the credit before your Indian return and any remittance are arranged.
If you will not be in Delhi to sign
A power of attorney executed abroad needs to be set up for the country in which you sign and the Delhi registration process in which it will be used. Apostille or consular formalities, adjudication or stamping after arrival in India, and any registration requirement should be confirmed by Delhi property counsel before you rely on the instrument. A short assumption about one step can delay the deed; start this review before the agreement is finalised.
Repatriation: plan the bank process before closing
Sale proceeds are ordinarily handled through the banking route and, for many NRI sellers, through an NRO account before remittance. RBI’s NRI remittance framework provides an annual USD 1 million facility from eligible NRO balances, subject to conditions, documentation, tax compliance, and the authorised dealer bank’s process. Amounts above the available facility or unusual fact patterns require the bank and, where necessary, RBI guidance.
For a high-value sale, discuss the remittance sequence with the authorised dealer bank and your CA before the deed is signed. Your bank will confirm the current document set, including the appropriate tax declarations/certificates, sale documents, PAN, passport, tax-credit evidence, and any source-of-funds records. Do not plan around a fixed bank turnaround time or a form number without that confirmation.
What remains non-negotiable
Consideration should move through banking channels and the sale deed should record the actual consideration. The payment trail, title file, tax deduction, and remittance documentation need to tell the same story. A clean file helps the current sale close properly and protects the next owner when the property is sold again.
Grey Beard’s role
Grey Beard coordinates the transaction process for NRI seller mandates: aligning the buyer, seller, CA, counsel, and bank documentation; keeping the TDS and certificate sequence visible; and helping the file move in the correct order. We do not provide tax or legal advice. Your CA and lawyer apply the law to your facts.
Selling South Delhi property from abroad?
Describe the location, approximate value, and how long you have held it. The Grey Beard team can coordinate the transaction process with your CA, lawyer, and authorised dealer bank.
Primary references
Finance Act, 2026 (Act No. 4 of 2026), assented 30 March 2026 — TAN exception for a resident individual or HUF purchasing immovable property from a non-resident, effective 1 October 2026.
Income Tax Department — section 397 and property-purchase TDS guidance — section 397 is the machinery for the deduction account number, depositing tax, and statements; it is not the provision under which the TDS certificate is issued.
CBDT Notification No. 121/2026 (G.S.R. 830(E)), 22 September 2026 — Income-tax (Fifth Amendment) Rules, 2026
RBI Master Direction — Remittance Facilities for Non-Resident Indians — NRO remittance framework and conditions.