TDS on NRI property sales: a practical reference
A clear guide to buyer withholding, the before-sale lower-deduction certificate, the post-deduction TDS certificate, current reporting, and remittance planning—without treating a general guide as a substitute for your CA, lawyer, or authorised-dealer bank.
By Ashutosh Bhogra · Updated October 2026
- In force since 1 October 2026: the TAN exception is limited to a resident individual or HUF purchasing immovable property from a non-resident. Confirm whether the buyer and transaction fall within that exception before relying on it.
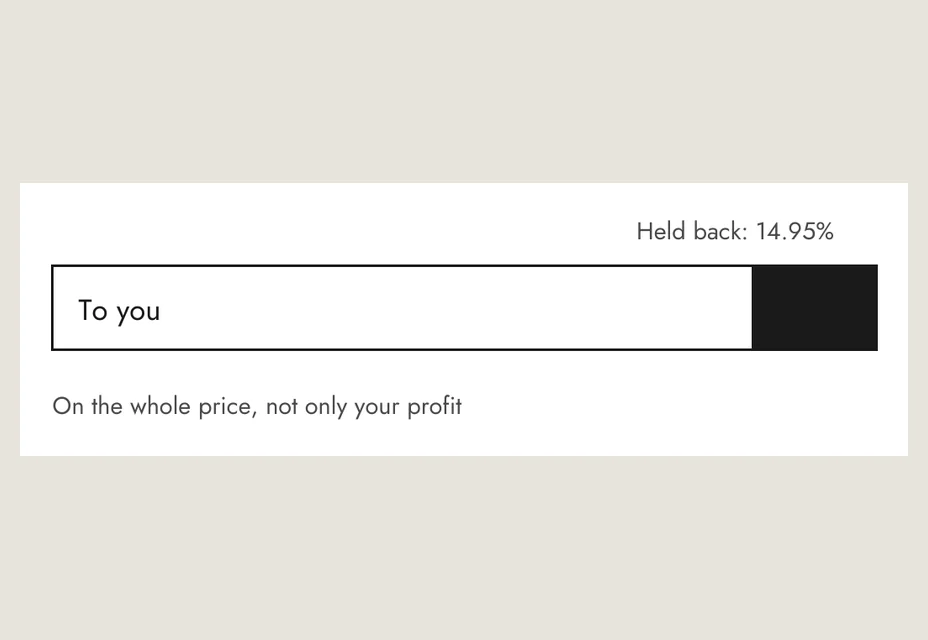
- The buyer holds back 12.5% plus surcharge plus cess (14.95% at these prices) on the whole price under section 393(2), unless a certificate lowers it.
- Sale completion and the money leaving India are separate steps, each with its own papers.
Information only. Tax, legal, and foreign-exchange treatment depends on the transaction, seller status, buyer status, certificate terms, and current portal requirements. Obtain written professional confirmation before payment or registration.
Start with the correct withholding framework
For payments or credits on or after 1 April 2026, withholding is governed by the Income-tax Act, 2025. For a non-resident seller, the buyer's obligation falls within section 393 and the related compliance/reporting framework in section 397.
More on the framework
For payments or credits on or after 1 April 2026, withholding is governed by the Income-tax Act, 2025. For a non-resident seller, the buyer’s obligation falls within section 393 and the related compliance/reporting framework in section 397. This is different from the simplified resident-seller property process.
The buyer should obtain transaction-specific CA advice before any payment, credit, or registration. The amount withheld is not automatically the seller’s final tax liability: final liability depends on the seller’s facts, available exemptions, treaty position where relevant, and the applicable rate/certificate.
The TAN relief is narrow
Since 1 October 2026, a resident individual or HUF buyer does not need a TAN to deduct tax when buying from a non-resident. No other buyer is covered.
More on the TAN relief
Since 1 October 2026, the Finance Act, 2026 gives a TAN exception for a resident individual or HUF deducting tax on consideration for transfer of immovable property from a non-resident. It does not create a blanket exemption for every purchaser. A company, LLP, partnership, or another buyer outside the statutory wording should not assume the exception applies.
Tax held back up to 30 September 2026 stays under the old TAN-based process. Since 1 October 2026, a resident individual or HUF buyer pays and reports the tax on Form 141, Schedule E, with their PAN, within 30 days from the end of the month in which it was held back. The tax department notified this on 22 September 2026 (Notification No. 121/2026).
A lower-deduction certificate can mean less money held back
The seller applies before the sale, under section 395(1), on Form 128 (earlier Form 13). It tells the buyer to hold back less than the standard amount.
More on the certificates
A lower- or nil-deduction certificate is applied for by the seller before the sale, under section 395(1), on Form 128 (earlier Form 13). It tells the buyer to hold back less than the standard amount. Section 397 is the machinery for the deduction account number, depositing tax, and statements; it is not the provision under which the TDS certificate is issued. The seller’s CA should prepare the application from the seller’s PAN, payer details, estimated income/tax computation, and supporting tax information. If a lower- or nil-deduction certificate is issued, the buyer should apply only the rate and conditions actually stated in it.
Begin the CA review well before the intended registration date. A signed agreement and buyer details are often important practical inputs for a property-specific application, but the documents, processing period, and certificate outcome depend on the case and should not be promised in advance.
The TDS certificate is given by the buyer to the seller after the tax has been deducted and paid, as proof. It is issued under section 395(4)(a), read with Rule 215, on Form 131 (earlier Form 16A). A resident individual or HUF buyer who uses the PAN route gives the certificate on Form 132 instead.
Buyer-side reporting matters after deduction
- Resident individual or HUF buyer
- Form 141, Schedule E, with PAN; certificate on Form 132
- Company, firm, LLP or non-resident buyer
- TAN; quarterly Form 144 (earlier 27Q); certificate on Form 131 (earlier 16A)
More on reporting
A buyer who still needs a TAN — a company, firm, LLP or non-resident — files the quarterly Form 144 (earlier Form 27Q). A resident individual or HUF buyer uses Form 141, Schedule E, for tax held back from 1 October 2026. The seller should ensure that the buyer’s compliance professional confirms the applicable deposit, statement, and TDS certificate steps for the transaction. The seller should retain the relevant tax evidence for their Indian return and any later bank/remittance request.
Form 141 is used for both, but the schedule differs: Schedule B is for a resident seller, Schedule E is for a non-resident seller. The buyer’s taxpayer status, the seller’s residential status, the payment/credit date, and the statutory exception all matter.
Capital-gains tax and TDS are not the same calculation
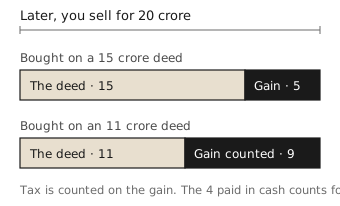
The tax held back is worked on the whole price; the tax you finally owe is worked on the gain. A CA works out both before payment.
More on the two calculations
The holding period, acquisition history, transfer expenses, eligible exemptions, surcharge, cess, other income, and any lower-deduction certificate can all affect the final position. The post-2024 long-term-gains framework is relevant, but no general website calculator should be treated as a binding tax computation or an instruction to the buyer on the exact amount to deduct.
Use the planning tool to organise basic sale and acquisition numbers, then have a CA calculate the formal return and withholding position before the parties fix payment mechanics.
As a high-value illustration, a ₹20 crore sale with a ₹10 crore documented acquisition cost has a gain of ₹10 crore before costs. The two calculators use the same rules to compare tax on gain with the section 393(2) no-certificate withholding estimate. A Lower Deduction Certificate may reduce cash withheld, but the buyer must follow the rate and terms actually issued and both parties should obtain CA confirmation before payment.
Repatriation requires a separate bank process
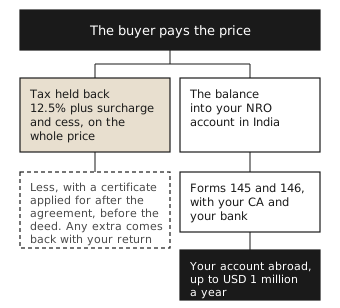
Sale completion and overseas remittance are separate steps. NRO balances may be repatriated within the RBI’s applicable facility, including the familiar USD 1 million per financial-year framework, subject to the RBI conditions and the authorised dealer bank’s document review. The exact remittance route, tax evidence, forms, and timing must be confirmed with the bank and CA handling the case.
A practical order of work
- 01Confirm the seller’s residential status, PAN, title, acquisition documents, and basic tax history with the CA.
- 02Agree the transaction structure and buyer details early enough for withholding and lower-certificate review.
- 03Have the buyer’s CA confirm the current TAN/PAN route, rate in force, deposit/reporting requirements, and whether the buyer qualifies for the no-TAN route.
- 04Retain the certificate, payment/withholding records, and return evidence before approaching the authorised-dealer bank for remittance.
Selling South Delhi property from abroad?
Grey Beard can coordinate the transaction sequence with the parties and their professionals. Tax filings, certificate applications, legal instruments, and bank remittance compliance should be completed by the qualified professional responsible for them.